Kenya Rental Income Tax Rules Face Overhaul Under 2026 Treasury Draft Regulations

Kenya’s National Treasury has proposed new 2026 regulations that would reshape how residential rental income is taxed, introducing mandatory electronic registration, monthly filing requirements, and tighter reporting obligations for landlords earning between KSh288,000 and KSh15 million annually.
Scope Of Kenya Rental Income Tax Under 2026 Treasury Regulations
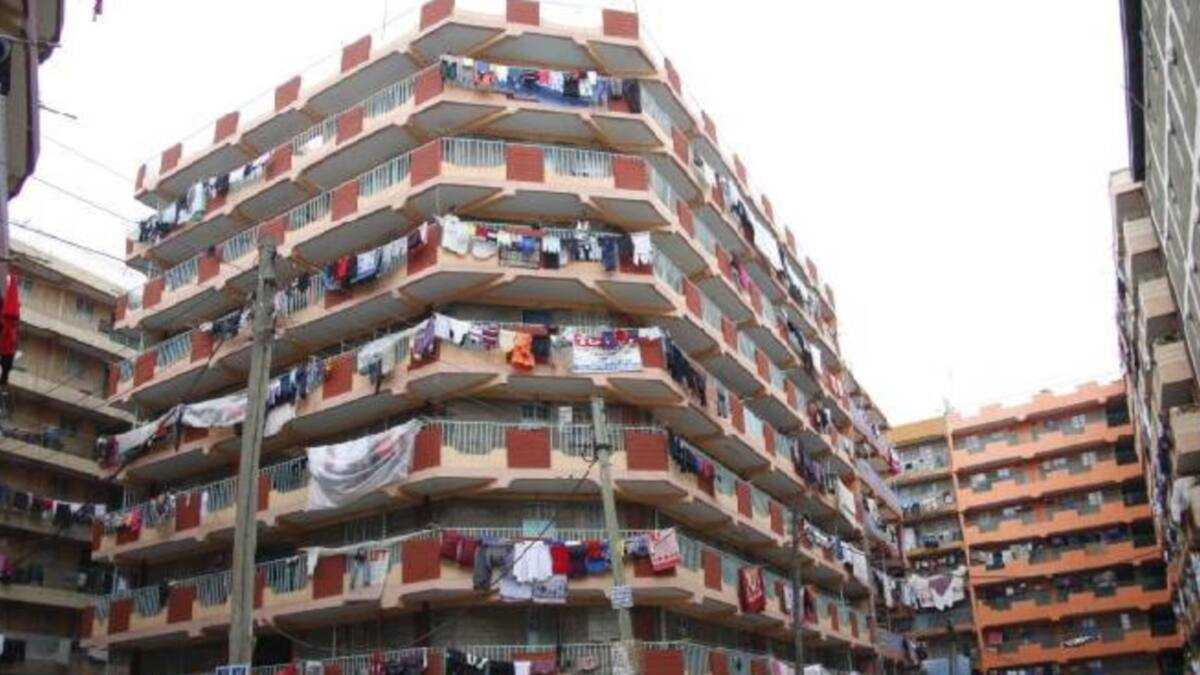
The draft rules, issued under section 130 of the Income Tax Act, are titled the Income Tax (Residential Rental Income Tax) Regulations, 2026 and would apply to resident persons deriving income from the use or occupation of residential property in Kenya. The regulations also extend to rental property owned by partnerships.
Under the proposed framework, “gross rent” is defined as payments received from granting another person the right to use or occupy immovable property, including rent, premiums or similar consideration linked to residential property use.
The regime applies to landlords whose rental income exceeds KSh288, 000 but does not exceed KSh15 million during any year of income. It excludes persons whose income is exempt under the First Schedule of the Income Tax Act.
Electronic Registration and KRA Monthly Rental Tax Filing Requirements
All affected landlords would be required to register their properties in an electronic system prescribed by the Commissioner. They would also be required to file monthly returns and pay the tax due on or before the 20th day of the month following receipt of rent.
A “tax period” is defined as a calendar month, while “property” refers to a building occupied as a residential house.
The regulations classify residential rental income tax as a final tax. Any income taxed under this regime will not be subject to any other tax under the Income Tax Act. At the same time, landlords will not be allowed to claim expense deductions or capital allowances when computing tax.
KRA Enforcement Powers and Compliance Requirements for Landlords
The Kenya Revenue Authority (KRA) would also be granted broad enforcement powers. The Commissioner may require landlords to produce books and records relevant to tax computation, appear at specified times and places, or update property details through the electronic system.
The rules also require taxpayers to maintain records necessary for determining tax liability in line with section 23 of the Tax Procedure Act.
Opt-Out Rules under Kenya Landlord Tax Regulations 2026
For landlords who choose not to be subject to the residential rental income tax regime, the draft regulations require formal notification to the Commissioner at least three months before the end of the year of income.
The Commissioner must acknowledge receipt within 60 days. If no acknowledgment is issued within that period, the notice is deemed received. Any opt-out takes effect in the following year of income.
Reporting Obligations for Landlords Exceeding Ksh15 Million Rental Income
The regulations also introduce a reporting obligation for higher-earning landlords. Where rental income exceeds KSh15 million, or where a taxpayer reasonably expects it to exceed that threshold, the Commissioner must be notified before the end of the year of income. Failure to notify constitutes an offence under the Act.
Submission of returns and payment of tax must be done by the 20th day of the month following the month in which rent is received. Non-compliance attracts penalties as prescribed under the Tax Procedure Act.
Disputes arising from the administration or assessment of the tax will be handled under the Tax Procedure Act.
The draft regulations also formally revoke the Income Tax (Residential Rental Income Tax) Regulations of 2016, replacing the existing framework with the proposed 2026 structure.
Impact of New Kenya Treasury Rental Tax Rules 2026 on Landlords
If implemented, the changes would tighten compliance requirements for residential landlords, particularly those operating multiple properties or structured through partnerships, while shifting reporting and payment obligations to a monthly cycle anchored on electronic systems.
Jefferson Wachira is a writer at Africa Digest News, specializing in banking and finance trends, and their impact on African economies.