The Untold Story of the Bond Platform CBK Doesn’t Want

Kenya’s government raises hundreds of billions each year through treasury bonds, but behind the scenes, a battle is simmering over who should control how those bonds are traded.
The East African Bond Exchange (EABX) Group Plc sits at the heart of the standoff. Licensed to operate as an over-the-counter (OTC) market, the platform is designed to bring transparency and lower costs to Kenya’s bond market.
Yet, despite approval from the Capital Markets Authority (CMA), it remains sidelined because the Central Bank of Kenya (CBK) has refused to allow it access to its bond settlement system.
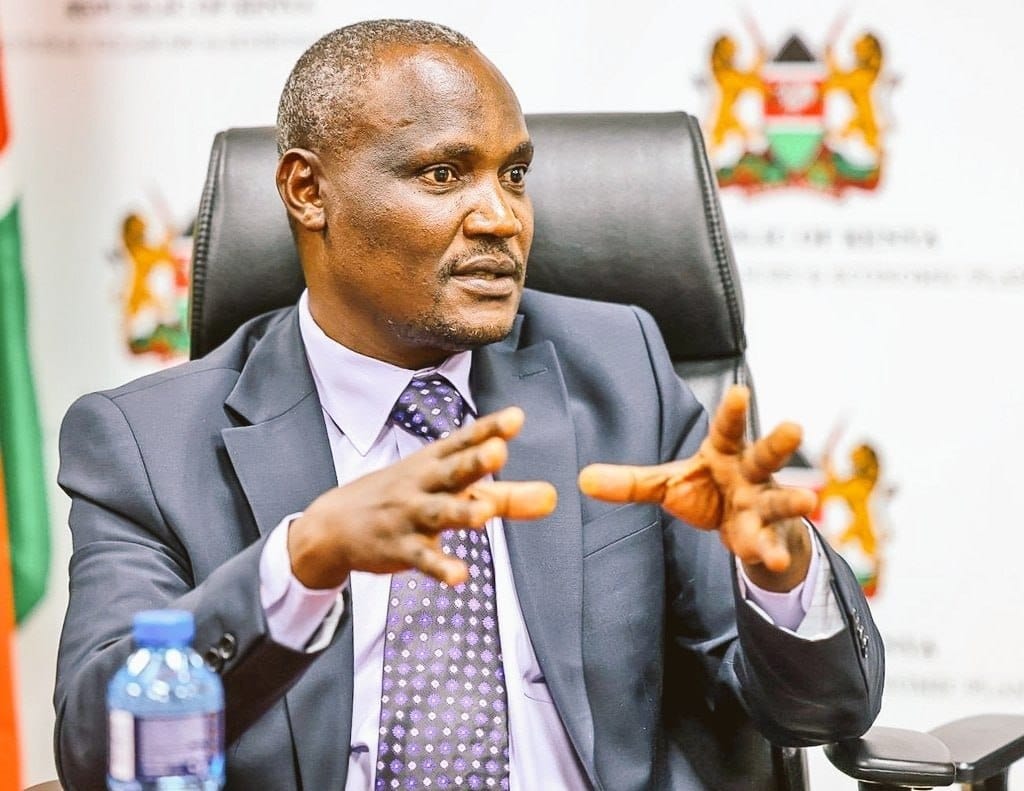
On September 17, 2025, executives from EABX met Treasury Cabinet Secretary John Mbadi in Nairobi to make their case. Their request was simple: integrate their platform with CBK’s Dhow Central Securities Depository (CSD), the digital settlement hub launched in 2023.
EABX argued that such a link would “unlock new investment avenues, enhance liquidity, and cut borrowing costs.” CBK, however, has rejected the idea, warning that parallel platforms could undermine monetary stability.
The Roots of EABX
The roots of EABX go back to 2009, when the Bond Market Association pushed for greater transparency in Kenya’s opaque OTC bond market. Over time, the initiative grew into a consortium of commercial banks under the Kenya Bankers Association, with support from partners such as FSD Africa.
In February 2024, the Capital Markets Authority approved EABX to operate as a self-regulatory OTC platform. Unlike the Nairobi Securities Exchange (NSE), which relies on brokers who charge commissions, EABX’s model allows buyers and sellers to negotiate directly.
This difference between EABX and the NSE is at the core of its pitch: faster trades at lower costs, without intermediaries.
What EABX Promises
Kenya’s public debt now stands at around 70% of GDP. To plug budget gaps, the government plans to borrow KSh 635.5 billion from domestic markets in the 2025/26 fiscal year. But bond yields remain high, between 10–15%, raising the cost of debt and limiting private sector credit.
EABX believes it can change this. Its model could lower yields by 50–100 basis points, attract regional investors, and deepen secondary trading. Banks, which hold about 45% of domestic bonds, see the platform as a chance to generate trading income, especially as margins from traditional lending narrow.
Yet, eight months after licensing, the platform remains idle. Without CBK approval to link to the DhowCSD, EABX cannot clear or settle trades. EABX CEO Terry Adembesa has described the delay as “unanticipated,” saying it has stalled a launch that could rival the NSE’s bond market operations.
Why CBK Is Saying No
CBK officials argue that the risks are too great. A dual system for trading the same government securities could create conflicting prices and distort the yield curve, a key benchmark for interest rates across the economy.
A CBK insider said the regulator fears two parallel government bond platforms could distort the yield curve, create dual pricing, and undermine the predictability of interest rates.
Instead of EABX’s model, CBK is piloting a system of “market makers”, which is banks tasked with continuously providing buy and sell quotes, to boost liquidity while keeping pricing centralized.
The regulator is also wary of the ownership structure. With no government stake in EABX and banks set to dominate trading, CBK fears the platform could give commercial lenders too much influence over a market central to public finance.
Treasury vs CBK
Treasury, however, sees value in EABX’s proposal. Its 2025 Medium-Term Debt Strategy includes plans to link OTC platforms like EABX to the DhowCSD, citing the potential to unlock liquidity and reduce borrowing costs.
That’s why the September 17 meeting with Mbadi was crucial for EABX. The group hoped Treasury would use its influence to push CBK toward cooperation. But for now, CBK’s position remains unchanged.
Meanwhile, CBK has been expanding access to its own system. Since its launch in August 2023, the DhowCSD has registered more than 80,000 users, offering retail investors direct access to government bonds without relying on brokers.
The Stakes for the Market
The outcome of this standoff carries major implications. For banks, EABX presents a potential new revenue stream through trading fees, helping offset pressure from high lending costs.
For the NSE and brokers, however, the platform threatens to erode hundreds of millions in commission revenue by diverting trades away from the exchange. Investors would gain more choice between EABX’s faster over-the-counter model and the NSE’s regulated environment.
At the macro level, without deeper secondary trading, government borrowing costs are likely to stay elevated, crowding out private credit and adding pressure on inflation.
EABX has maintained an optimistic public stance, posting recently that it remains committed to “enhancing capital market reforms.” But without CBK’s approval, the platform remains stuck.
Jefferson Wachira is a writer at Africa Digest News, specializing in banking and finance trends, and their impact on African economies.