Kenyan Farmers to Get Up to 80% Financing for Kubota Tractors Under Co-op Bank Deal

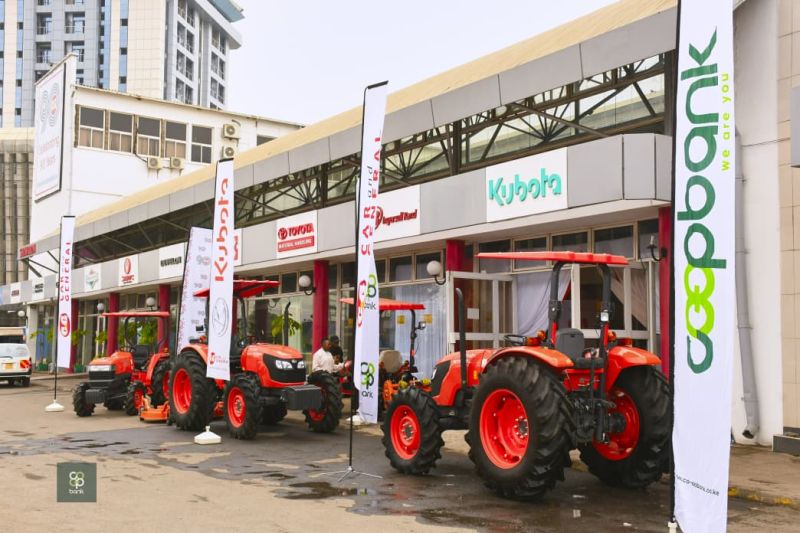
Co-operative Bank of Kenya and Car & General have partnered to make agricultural mechanisation more accessible to Kenyan farmers through flexible financing for Kubota tractors and agricultural equipment.
The partnership provides financing of up to 80 percent of the value of eligible Kubota tractors and machinery, reducing the upfront capital required by farmers seeking to acquire modern agricultural equipment.
Under the financing arrangement, customers are required to provide a minimum 20 percent deposit, while the balance is financed through Co-operative Bank’s asset finance facility.
The initiative targets farmers seeking to improve productivity by adopting tractors and specialised agricultural implements without committing the full purchase price in cash.
Co-operative Bank Offers Up to 80% Tractor Financing
The financing structure allows farmers to acquire Kubota tractors and agricultural machinery with up to 80 percent of the asset value financed by Co-operative Bank.
The tractor or other financed equipment typically serves as the primary collateral for the facility. This enables farmers to use the asset being purchased to secure the financing rather than relying solely on other forms of collateral.
Customers are required to make a minimum 20 percent contribution towards the purchase price. The remaining amount is financed by the bank under agreed asset finance terms. Repayment periods can be structured around crop harvest cycles, allowing agricultural customers to align their loan repayments with seasonal farm revenues.
Financing Designed to Reduce Upfront Equipment Costs
The partnership addresses one of the main costs associated with agricultural mechanisation: the high initial capital required to purchase tractors and equipment.
Instead of paying the full cost of a Kubota tractor upfront, farmers can preserve part of their available capital while financing the equipment through the bank. This leaves farmers with more working capital for other agricultural expenses, including seeds, fertiliser and fuel.
The financing is also provided through established financial and equipment institutions, giving customers a formal process for equipment acquisition and loan financing.
How Farmers Can Access Kubota Tractor Financing
Farmers seeking to acquire Kubota tractors through the financing arrangement can begin by selecting the equipment required for their operations.
Customers can visit a Car & General showroom to identify a Kubota tractor model suitable for their farm and obtain a proforma invoice showing the cost of the tractor, attachments and other equipment included in the purchase.
The proforma invoice can then be presented to a Co-operative Bank branch as part of the financing application.
The bank will assess the customer’s creditworthiness and financial capacity. Farmers may be required to provide financial records, including bank statements or evidence of seasonal farming revenues, to support the credit assessment.
Once the facility is approved, the customer makes the required minimum 20 percent contribution under the agreed financing structure. Co-operative Bank then releases the financed amount to Car & General, allowing the farmer to take delivery of the equipment.
The arrangement also provides access to training and after-sales support associated with the machinery.
Financing Terms for Kubota Agricultural Equipment
Under the partnership, farmers can finance up to 80 percent of the value of eligible Kubota tractors and agricultural machinery. The customer contribution starts at 20 percent of the asset value, while repayment periods are structured to accommodate agricultural cash-flow cycles.
The financing covers Kubota tractors and specialised agricultural implements, allowing farmers to acquire equipment suited to different farming activities.
The structure is intended to reduce the capital barrier associated with mechanisation while enabling farmers to retain cash for day-to-day farming requirements.
Costs Farmers Need to Consider
Farmers taking up asset financing for agricultural machinery will also need to account for costs associated with the financing agreement. Comprehensive insurance is required for the financed asset throughout the loan period, creating an additional recurring cost for the borrower.
Other costs can include loan processing and statutory charges, valuation fees, bank negotiation fees and the installation of tracking equipment where required under the financing agreement.
Farmers also need to meet their repayment obligations throughout the agreed loan period. Failure to make scheduled payments can result in recovery or repossession of the financed tractor, depending on the terms of the asset finance agreement.
The value of agricultural machinery can also decline over time through depreciation, while the outstanding loan balance reduces according to the repayment schedule.