Ecobank Uganda Launches eMCA Giving Merchants Access to Up to UGX 70 Million

Ecobank Uganda has launched the Electronic Merchant Cash Advance (eMCA), a digital financing solution that allows eligible merchants to access short-term working capital based on their transaction performance.
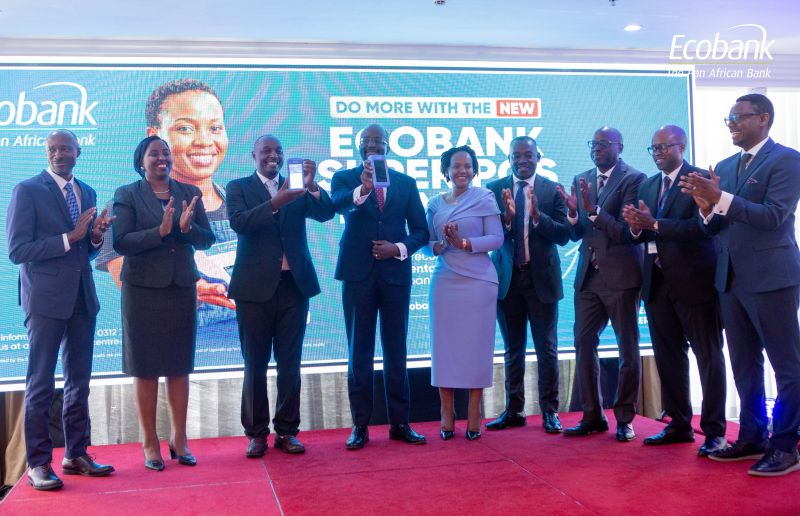
The product was launched at the Sheraton Hotel Kampala in an event attended by Ecobank Uganda Board Chairman David F.K. Mpanga, Managing Director Grace Muliisa, customers, partners and other stakeholders.
The launch was officiated by Hon. Eng. Rt. Hon. Eng. Asiimwe Jonard, Minister of State for Science, Technology and Innovation, as the Chief Guest.
How Ecobank Uganda eMCA Works
The Electronic Merchant Cash Advance uses a merchant’s digital transaction history to determine the amount of working capital they can access. Under the facility, eligible merchants can borrow up to 50% of their average monthly digital collections, subject to a maximum financing limit of UGX 70 million.
Ecobank Uganda charges a fixed 3% access fee on the financing advanced. Businesses must also have an active digital collections history with Ecobank Uganda for at least three months before the automated credit system can generate a borrowing limit.
The model allows the bank to assess merchants using their transaction activity rather than relying solely on conventional lending requirements.
Ecobank Uganda already provides businesses with digital collection tools including Point-of-Sale terminals and other electronic payment solutions. Its commercial banking platform also offers digital tools for collections and cash management.
Who Can Access eMCA?
The Ecobank Uganda eMCA facility primarily targets Micro, Small and Medium Enterprises (MSMEs) and established merchants that generate sales through digital channels.
The initial target group includes existing Ecobank Uganda merchants using the bank’s collection infrastructure, including POS terminals, online payment gateways and QR-based payment solutions.
The product also addresses smaller businesses that may have limited accounting records but maintain consistent digital transaction activity.
For such businesses, transaction data can provide the bank with a record of sales performance that can be used in determining access to short-term financing.
Ecobank Uganda’s existing business banking offering includes EcobankPay QR payments, Omni Lite and other digital solutions designed to help businesses manage payments and banking services.
Another eMCA target group is entrepreneurs who may struggle to obtain conventional bank financing because they do not have physical assets such as land or commercial property to pledge as collateral.
By linking borrowing capacity to digital collections, eMCA provides a different basis for assessing short-term working-capital needs.
The financing can be used for purposes such as restocking, managing cash flow, expanding business operations and responding to new commercial opportunities.
Ecobank Uganda already offers other business lending products, including overdrafts and revolving credit facilities, but eMCA introduces a transaction-based approach to determining merchant financing.