KCB Loses Sh2,050 Mobile Money Transfer Case as Court Orders Banks to Act Fast on Wrong Payments

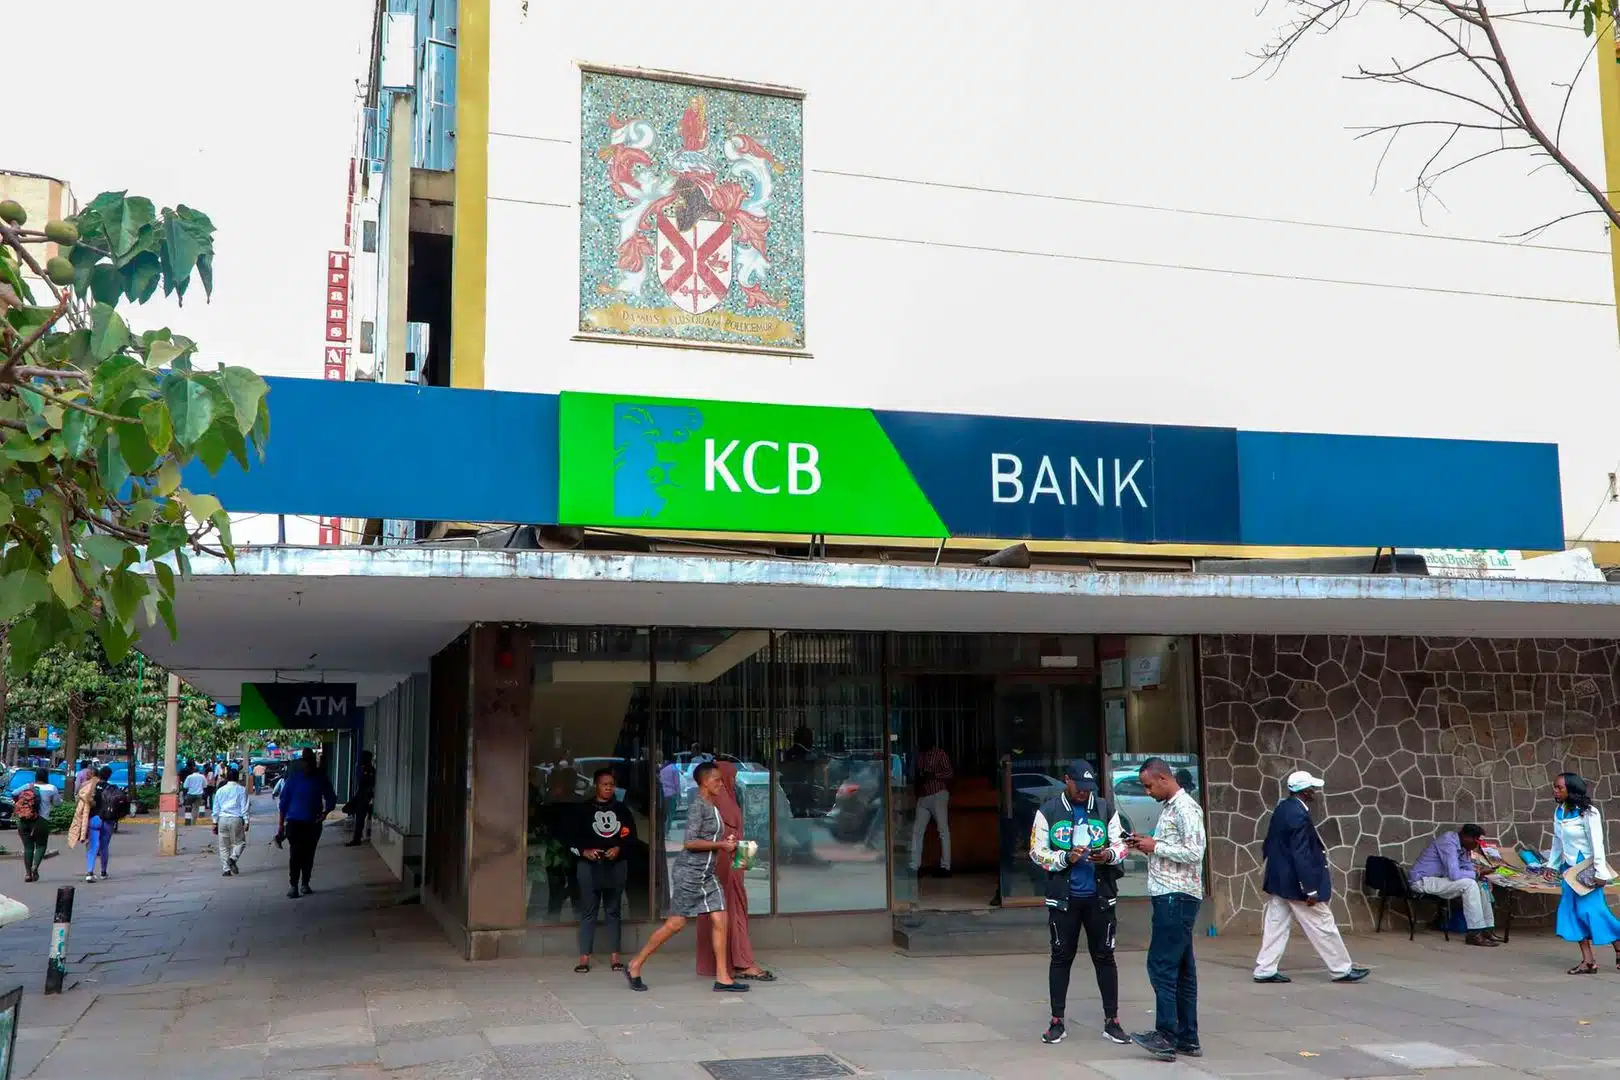
Kenya Commercial Bank (KCB) has lost a three-year legal battle over a Sh2,050 mistaken mobile money transfer after the High Court ruled that banks have a legal duty to act immediately once customers report erroneous electronic payments.
Justice Joseph Sergon upheld an earlier Small Claims Court decision, finding that financial institutions must take reasonable and prompt measures to preserve disputed funds after receiving notification of a wrong transaction.
The case originated in February 2023 when Nakuru-based advocate Sammy Kamonjo Kiburi mistakenly sent Sh2,050 through Safaricom M-Pesa to the wrong KCB Paybill number.
Upon realising the mistake, Kiburi immediately contacted both Safaricom and KCB to report the erroneous transaction and request that the funds be secured.
However, instead of immediately freezing the disputed amount, KCB’s customer service process involved escalating the complaint through internal channels from its headquarters to a local branch.
The delay allowed the recipient of the mistakenly transferred funds to withdraw the money before the bank could secure it.
Kiburi later requested a refund and sought information about the recipient who had withdrawn the funds. KCB declined to reimburse the money and refused to disclose the recipient’s identity, citing customer confidentiality obligations.
The advocate subsequently sued the bank at the Small Claims Court, where he won the case. KCB challenged the decision, leading to a three-year appeal process that eventually reached the High Court.
KCB Argues Customer Was Responsible for Mistake
During the appeal, KCB argued that Kiburi was responsible for the loss because he had entered the wrong Paybill number when initiating the transaction.
The bank maintained that it could not reverse the transfer without the recipient’s consent and that revealing the identity of the recipient would violate customer confidentiality rules.
KCB also argued that the sender’s mistake amounted to contributory negligence, meaning the customer should bear responsibility for the lost funds.
However, the High Court rejected the arguments, ruling that while customers must exercise care when making electronic payments, banks have a separate obligation to act once they are notified of an error.
Court Finds KCB Negligent for Delayed Response
Justice Sergon ruled that KCB failed to demonstrate the steps it took between receiving Kiburi’s complaint and the withdrawal of the funds.
The court acknowledged that banks cannot independently reverse completed transactions without approval from the recipient. However, it stated that financial institutions have a responsibility to immediately preserve disputed funds while investigations are ongoing.
The judge found that internal procedures and administrative delays could not be used as a defence where a customer had promptly reported an erroneous transaction. According to the ruling, a bank’s operational processes should not disadvantage customers who have acted quickly to correct genuine payment mistakes.
The judgment establishes that banks and financial institutions must urgently respond to reports of mistaken electronic transfers. Where a customer notifies a bank promptly, the institution is expected to take immediate steps to secure the funds before they can be withdrawn.
Failure to preserve the disputed money could expose banks to financial liability if delays within their systems allow recipients to access the funds. The ruling effectively shifts responsibility for system delays and slow internal processes from customers to financial institutions.
The High Court also addressed KCB’s refusal to disclose the identity of the recipient who withdrew the money. Justice Sergon ruled that banks cannot rely on customer confidentiality to prevent victims of mistaken payments from pursuing recovery options.
The court noted that disclosure of recipient details may be necessary where a customer is attempting to recover funds sent incorrectly.
KCB’s own witness acknowledged that the recipient’s identity could have been shared, weakening the bank’s argument that confidentiality prevented disclosure.