NCBA and Stanbic Fixed Deposit Accounts Explained: Which Delivers Better Value?

Fixed deposit accounts remain one of the most predictable ways for Kenyan savers to earn returns while preserving capital. They appeal to individuals, businesses, and institutions seeking fixed yields over a predetermined investment period without exposure to stock market volatility.
Among Kenya’s leading lenders, NCBA and Stanbic Bank fixed deposit accounts cater to different customer profiles. While NCBA focuses on rewarding larger deposits and longer commitments, Stanbic emphasizes accessibility, flexible tenures, and liquid savings alternatives.
NCBA Fixed Deposit Account Explained
NCBA structures its fixed deposit portfolio around investors willing to commit larger amounts over relatively longer periods.
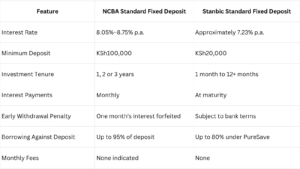
The bank’s Standard Fixed Deposit Account offers interest rates averaging between 8.05% and 8.75% per annum across standard retail categories. Pricing is derived from the lender’s quarterly Funds Transfer Pricing (FTP) benchmark, creating a framework that moves alongside prevailing market conditions.
Investors are restricted to tenures of one year, two years, or three years, making the account more suitable for savers with clearly defined investment horizons.
To access the preferred retail pricing bands, customers are generally expected to maintain deposits of at least KSh100,000.
Interest accrues daily based on the closing account balance but is paid monthly into a designated NCBA transactional account. This feature may appeal to investors seeking a regular income stream while keeping their principal amount intact.
- Early Withdrawal Penalties at NCBA
NCBA imposes relatively strict rules on premature withdrawals.
Investors who liquidate their deposits before maturity forfeit one month’s interest. In addition, any interest accumulated between the last interest payment date and the liquidation date is lost.
Such penalties make the account more appropriate for funds that are unlikely to be needed during the investment period.
- Borrowing Against an NCBA Fixed Deposit
One notable feature is the ability to leverage an active deposit to access credit.
Customers may secure a Cash Covered Loan of up to 95% of the deposit value, offering access to short-term financing without terminating the investment. However, the loan must be fully settled at least 30 days before the deposit reaches maturity.
- NCBA’s Fixed Income Basket Note Fund
Beyond traditional fixed deposits, NCBA also offers a premium investment solution through its Fixed Income Basket Note Fund. The product targets institutional investors and affluent retail clients transacting through the bank’s Investment Banking division.
Indicative returns include:
- 10.00% per annum for three months
- 10.25% per annum for six months
- 10.50% per annum for investments between 12 and 24 months
These returns exceed those available under the standard retail fixed deposit account, although eligibility and investment amounts may differ substantially.
Stanbic Bank Fixed Deposit Account Features
Stanbic Bank takes a different approach by emphasizing accessibility and tenure flexibility. Its Standard Fixed Deposit Account offers average returns of approximately 7.23% per annum for conventional retail investment sizes.
Unlike NCBA’s fixed tenure structure, Stanbic allows customers to select investment periods ranging from one month to more than 12 months, giving savers greater control over maturity dates. The bank also maintains a significantly lower entry barrier.
Customers can open a fixed deposit with as little as KSh20,000, making the product accessible to a wider range of investors. There is no publicly indicated maximum investment limit.
- Interest Payment Structure at Stanbic
Stanbic follows a maturity-based payout model. Funds remain untouched during the agreed investment period, and interest is calculated using the contracted rate before being paid alongside the principal upon maturity.
The account operates under a free banking structure, with no monthly management charges applicable.
- Stanbic PureSave Account as an Alternative
For investors seeking better liquidity, Stanbic’s PureSave Account provides an alternative to traditional fixed deposits. Rather than locking funds away for a predetermined period, the account calculates interest daily and credits earnings on the first day of the following month.
A distinctive incentive within the account is the 1% bonus interest rate available to customers who make no withdrawals for a continuous 12-month period. PureSave customers also enjoy one free over-the-counter withdrawal each month.
Another feature is access to pre-approved credit facilities. Eligible account holders may obtain advances or personal loans amounting to as much as 80% of their accumulated savings balance.