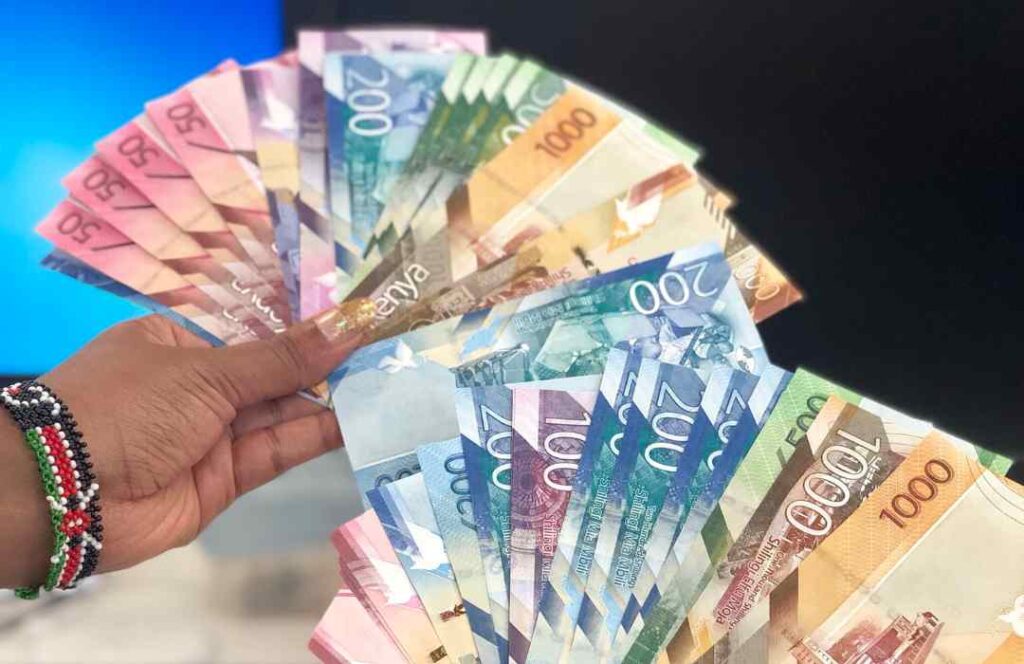
The Shift from Overdrafts to Salary Advances in Kenya

Salaried workers are increasingly ditching traditional bank overdrafts for salary advances, a shift reshaping how short-term credit is accessed. Once dominated by overdraft facilities that allowed withdrawals beyond account balances, the market has tilted toward payroll-linked loans that promise faster approvals, easier access, and repayment through direct salary deductions.
From Overdrafts to Salary Advances
For decades, overdrafts were a staple product for salaried employees. These revolving facilities allowed account holders to withdraw beyond their balance up to a pre-approved limit, with interest charged only on the amount used. The best bank overdrafts in Kenya provided flexibility, but often required strong credit histories, collateral, or employer guarantees.
By 2024, overdrafts became increasingly expensive. With benchmark interest rates averaging 13% and effective borrowing costs often exceeding 20% annually once fees were factored in, overdrafts lost appeal.
High-value overdraft bookings rose modestly to Sh35.61 billion in late 2023 but then stagnated as workers sought cheaper, faster, and more predictable alternatives.
At the same time, salary advances in Kenya gained traction. A Salary Advance is a short-term loan issued to salaried customers based on their income profile, usually between 50% and 150% of net monthly pay.
Unlike overdrafts, which revolve, advances are lump-sum disbursements repaid directly through salary deductions in the following month or within a set tenure.
The Economic Pressures Behind the Shift
This pivot is rooted in Kenya’s challenging economic environment. Inflation peaked at 9.6% in late 2022 before easing to about 5% by mid-2025, but food and energy costs remained volatile.
Salaried workers also faced compulsory deductions: 1.5% for housing, 2.75% for social health insurance, and higher pension contributions. These policies significantly reduced take-home pay for teachers, civil servants, and private-sector professionals.
Meanwhile, non-performing loans climbed to 16.4% in 2024, the highest in a decade, forcing banks to tighten unsecured lending. Overall personal and household credit shrank by Sh138 billion to Sh943.84 billion. Yet, salary advances bucked this decline as banks leaned toward low-risk, payroll-secured lending.
Salary Advances on the Rise
The numbers tell the story. In the nine months ending September 2023, Co-operative Bank’s salary advances surged 3.5 times to Sh51.67 billion from Sh14.67 billion a year earlier. They made up the bulk of its Sh56 billion in new digital loans by September 2024.
Equity Bank disbursed advances of up to Sh300,000 with interest rates ranging between 13% and 20.5%. Salary Advance KCB products were capped at Sh100,000–Sh250,000 with a flat monthly rate of 8%. NCBA provided similar facilities with repayment periods extending up to six months.
Even though annualized borrowing costs for salary advance loans can be as high as 60%, workers have embraced them because of their accessibility and speed. Many products now come as online salary advance loans, offered via mobile apps that process requests within hours.
Stanbic Bank’s mobile platform, for instance, allows instant borrowing from Sh1,000 to Sh500,000, repayable in one month, with no paperwork or long approvals.
Digitalization and Employer Involvement
Banks are not the only players driving this change. Employers have integrated advances into payroll systems, enabling seamless deductions. Many companies see these facilities as staff retention and productivity tools. According to a World Bank study, access to salary advances reduces financial stress, improving employee performance.
This integration aligns with Kenya’s rapid digital banking shift. Instead of renewing overdraft facilities every year with heavy paperwork, employees can now tap into salary advance loans online using nothing more than a mobile app and three months’ salary history.
Risks and Considerations
For consumers, advances provide relief during mid-month financial squeezes. But financial experts caution that the convenience comes with risks. Advances carry high annualized costs, and without budgeting discipline, workers may fall into cycles of dependency.
For banks, however, the model offers security. Automated payroll deductions lower default risks, allowing lenders to maintain profitability even as other personal loan products contract.
Jefferson Wachira is a writer at Africa Digest News, specializing in banking and finance trends, and their impact on African economies.

